In this article (14 sections)
- What inverse condemnation means in a wildfire case
- Why private utilities are covered
- Inverse condemnation wildfire claims: what they cover and what they don’t
- How the rule applies to the Eaton Fire
- Could the rule change?
- Inverse condemnation vs. negligence: a side-by-side look
- Key Terms in an Inverse Condemnation Claim
- How Insurance Companies Use Inverse Condemnation
- Deadlines and Timing in Inverse Condemnation Cases
- How Property Owners Can Prepare an Inverse Condemnation Claim
- Renters, Landlords and Business Owners
- Questions to Ask a Law Firm About Inverse Condemnation
- Frequently asked questions
- How Direct2Attorney can help
Last updated: October 2026
Under California’s inverse condemnation doctrine, wildfire victims generally don’t have to prove a utility was careless. They must show that the utility’s equipment, used for a public purpose, was a substantial cause of damage to their property. If they can, the utility may owe compensation even if it followed safety rules. Because inverse condemnation shapes how many California fire claims are handled, this guide also explains key terms, timing and how insurers use the same rule.
This rule is a big reason Eaton Fire property claims against Southern California Edison (SCE) look different from wildfire cases in most other states.
What inverse condemnation means in a wildfire case
The California Constitution, Article I, Section 19, says private property may be taken or damaged for public use only with just compensation. Usually the government starts that process. “Inverse” condemnation is when the property owner brings the claim instead.
In a wildfire case, the argument is simple. A utility’s power lines serve the public. When that system damages private property, the owner should be paid, like any other public project that causes harm.
What a property owner generally has to show
- The damage came from a public improvement, such as a power line, as it was designed, built or run
- Real or personal property was physically damaged
- The equipment was a substantial cause of the damage
As one legal overview explains, neither fault nor foreseeability generally needs to be shown.
Why private utilities are covered
SCE and PG&E are private companies, not government agencies. So why does a rule about public use apply to them?
In Barham v. Southern California Edison (1999), a California appeals court said a regulated private utility can be liable in inverse condemnation. It reasoned that such utilities act more like government entities than like private companies. A 2012 case, Pacific Bell v. Southern California Edison, followed that ruling.
In 2019, the California Supreme Court in City of Oroville v. Superior Court refined the test. It said the damage must come from the inherent risks of the public improvement as it was designed, built or maintained.
Inverse condemnation wildfire claims: what they cover and what they don’t
Inverse condemnation is about property. It can support claims for:
- Homes and other structures
- Personal belongings
- Loss of use, such as rental value
- Some economic losses tied to the property
It does not cover personal injury, wrongful death or emotional distress. Those claims usually rely on other legal theories, such as negligence, which do require proof of fault.
State law also lets a winning property owner recover reasonable attorney, appraisal and engineering fees in these cases. That can affect how cases are handled and settled.
Why negligence still matters
Most wildfire lawsuits bring both kinds of claims. Plaintiffs’ lawyers in the Eaton case say SCE failed to properly inspect, maintain and operate its equipment. Proving fault can open the door to damages that inverse condemnation doesn’t reach.
How the rule applies to the Eaton Fire
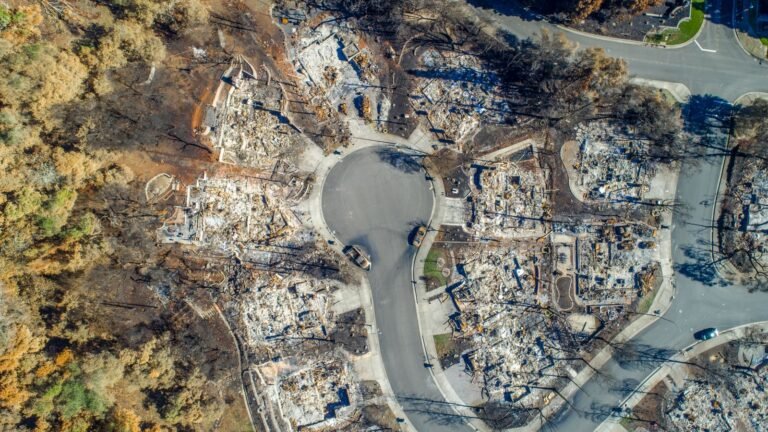
On August 4, 2026, Los Angeles County Fire and CAL FIRE concluded that arcing on an out-of-service SCE transmission tower started the Eaton Fire. That report goes to causation, which is central to an inverse condemnation claim.
For property owners, that shifts the focus. Under inverse condemnation, the key questions often become what was damaged and what it is worth, rather than whether SCE was careless.
SCE had already acknowledged that its equipment was associated with the fire’s start, LAist reports. The first bellwether trial is set for January 25, 2027.
SCE has also filed cross-claims blaming Los Angeles County and others for making the damage worse. In July 2026, Judge Laura Seigle let a narrow vegetation claim against the county go forward while dismissing broader theories, Hoodline reported.
Could the rule change?
Utilities and some state officials argue the rule is unfair when a utility did nothing wrong. A California Earthquake Authority report required by SB 254 recommended in April 2026 replacing it with a fault-based standard for utility fires. That change would likely need a constitutional amendment.
As of October 2026, lawmakers had not made that change. A late-session wildfire bill was postponed until fall. Any future change could raise questions about which fires it applies to. For now, the existing rule remains California law. A participating law firm can explain how any new proposal might affect a specific claim.
Want to see how this rule has played out before? Read our look at past utility wildfire settlements.
Inverse condemnation vs. negligence: a side-by-side look
Wildfire lawsuits usually use both theories. Here is how they compare in plain terms.
Inverse condemnation
- What you must show: The utility’s equipment was a substantial cause of damage to your property.
- Fault needed? Generally no.
- What it covers: Property damage and related losses, such as loss of use.
- Fees: A winning owner can recover reasonable attorney, appraisal and engineering fees.
Negligence
- What you must show: The utility failed to act with reasonable care, and that failure caused your harm.
- Fault needed? Yes.
- What it covers: Property losses plus injury, wrongful death and emotional distress.
- Other possible damages: In some cases, plaintiffs also seek punitive damages, which require more proof.
An example
Suppose a tree branch falls into a well-kept power line during a windstorm and starts a fire. The utility may have done everything right. Under inverse condemnation, it may still owe property owners for the damage.
The state’s utility consumer advocate has pointed to a similar case: a palm frond blowing into a line. In its 2023 policy paper, it said the utility may be liable for that fire’s property damage.
Why utilities argue for change
Utilities say this rule makes them pay for fires they couldn’t prevent. They also say those costs end up on customers’ bills. Victims’ advocates respond that the rule puts the risk on the company that runs the equipment, not on the families who lost homes.
Key Terms in an Inverse Condemnation Claim
Court papers and news stories about inverse condemnation use terms that are rarely explained. This plain-language glossary can help you follow them.
- Just compensation: the payment the California Constitution requires when private property is taken or damaged for public use.
- Taking vs. damaging: a “taking” means property is acquired or occupied. “Damaging” means it is harmed. Wildfire cases are usually about damaging.
- Public improvement: a project or system that serves the public, such as power lines, water systems or roads.
- Public use: the reason the improvement exists, such as delivering electricity to homes and businesses.
- Substantial cause: the improvement must be a substantial cause of the damage, not just a remote or minor factor.
- Inherent risk: the risk that comes with the improvement as it was designed, built or maintained, a test the California Supreme Court described in the City of Oroville case.
- Condemnor: the government agency or utility that takes or damages property. In a wildfire case, that is usually the utility.
- Subrogation: an insurer’s right to seek repayment for claims it already paid.
Why the words matter
These terms set the boundaries of a claim. For example, “substantial cause” is about the link between the equipment and the damage, not about whether anyone was careless. Knowing that helps explain why inverse condemnation claims focus so heavily on causation and property values.
The idea behind the rule
The Cozen O’Connor overview traces the rule back to a basic fairness principle from a California Supreme Court case, Belair v. Riverside County Flood Control District. The idea is that the costs of a public improvement that benefits the community should be spread among those who receive the benefit.
In a utility fire case, that means the cost of damage is meant to fall on the system that serves many customers, rather than on the few families who lost their homes. Critics argue this shifts costs to all ratepayers. Supporters say that is exactly the point.
How Insurance Companies Use Inverse Condemnation
Homeowners are not the only ones who rely on this rule. Insurance companies use it too, and that affects how wildfire cases unfold.
Subrogation in plain terms
When your insurer pays your claim, it usually gains the right to seek that money back from whoever caused the loss. A subrogation overview by the law firm Cozen O’Connor notes that inverse condemnation is available to a subrogating insurance carrier. That means insurers can often use the same no-fault rule that homeowners use.
What that means for you
- Your insurer’s claim against the utility is usually separate from yours.
- Insurers often settle as a group, sometimes before individual survivors do.
- Your own claim usually focuses on what insurance did not cover, such as losses above your limits, deductibles and items your policy excluded.
Why underinsured losses matter
After large fires, many families find that their coverage falls short of the cost to rebuild. Those uninsured and underinsured amounts are often at the center of an individual inverse condemnation claim. Careful records of what your insurer paid, and what it did not, can make that gap easier to show.
Watch for double counting
A loss that your insurer already paid generally should not be claimed twice. Keep a clear list of payments by category, such as dwelling, contents and living expenses. A participating law firm can help sort out which losses remain.
Deadlines and Timing in Inverse Condemnation Cases
Timing rules differ depending on the type of claim and who is being sued. Getting them wrong can end a claim, so it helps to understand the basics early.
General timing rules
The Cozen O’Connor overview describes a three-year deadline to file an inverse condemnation cause of action in California. It contrasts that with a much shorter, six-month requirement to file a government claim for many other claims against public entities.
These are general rules, and there can be exceptions. Your own dates depend on the facts, the type of claim and the parties involved. A participating law firm can review your timeline.
Why other claims may have different dates
Most wildfire lawsuits also include negligence and other claims, which may have their own deadlines. Claims for personal injury or wrongful death are not covered by inverse condemnation at all. Each one may run on a separate clock.
Claims against public agencies
SCE’s cross-claims against Los Angeles County, and the Palisades Fire cases against the City of Los Angeles and the State, show that public agencies can be involved too. Claims against government bodies often have special notice steps and short deadlines. Do not assume the rules for a utility claim apply to an agency.
Build a simple date list
Keep one page with the dates that may matter to your claims. Include the date of the fire, the date you first returned to your property, the dates of key insurance letters and the date of any offer you received.
Add the August 4, 2026 release of the official cause report, since it may matter when your dates are reviewed. Bring this list to any meeting with a law firm so it can check your deadlines quickly.
SCE’s program is a different deadline
SCE’s direct compensation program has its own deadline of November 30, 2026, according to SCE’s program page. That date is not a court deadline. It only applies to filing with the program.
How Property Owners Can Prepare an Inverse Condemnation Claim
Since fault generally is not the main question in an inverse condemnation claim, the work often shifts to proving what was damaged and what it was worth. Good preparation can make that easier.
Gather proof of ownership and condition
- Deeds, property tax records and mortgage statements
- Photos or videos of the property before the fire, including from real estate listings
- Records of upgrades, remodels and permits
- Landscaping, fencing and outbuildings that were part of the property
Document the damage
- Photos and video taken after the fire, once officials allow access
- Debris removal and testing records
- Repair estimates, rebuild bids and engineering reports
- Smoke and ash test results for homes that did not burn
Track related losses
- Rent and living costs while you are out of your home
- Lost rental income if you owned a rental property
- Costs for appraisals, engineers or other professionals you hired
State law allows a winning property owner to recover reasonable attorney, appraisal and engineering fees in these cases. Keep invoices for any professionals you hire.
Renters, Landlords and Business Owners
Inverse condemnation is about damage to property, and property is not limited to houses. Different kinds of owners may have different kinds of losses.
Renters
Renters do not own the building, but they own what was inside it. Furniture, clothing, electronics and other belongings are personal property. A renter’s own losses may be part of a claim, separate from the landlord’s.
Landlords
Owners of rental homes may have losses for the structure itself and for rental income they could no longer collect. Keep leases, rent records and tax returns that show what the property earned before the fire.
Business owners
Businesses may have damaged buildings, equipment, inventory and supplies. Some business losses tied to the property may be covered, while others may depend on negligence or other theories. An accountant and a participating law firm can help sort out which records matter most.
Questions to Ask a Law Firm About Inverse Condemnation
If you talk with a participating law firm, these questions can help you understand how the rule may apply to your claims.
- Which of my losses fall under inverse condemnation, and which depend on proving negligence?
- What deadlines apply to each of my claims, and which dates should I track?
- How will you prove the value of my home and belongings?
- Will you work with appraisers or engineers, and how are those costs handled?
- How does my insurer’s subrogation claim affect my own claim?
- If state lawmakers change the rule, how could that affect my case?
- How are your fees figured, and can I see the agreement in writing?
Write down the answers and keep them with your other records, along with the date of each conversation. Clear answers help you compare options and make decisions at your own pace.
Do not forget other claims
Inverse condemnation covers property, but your family may also have claims for injury, emotional distress or wrongful death. Those depend on other legal theories. A participating law firm can explain how the different claims fit together for your household.
Frequently asked questions
Do I have to prove Edison was negligent?
Not for property claims under inverse condemnation. You generally must show SCE’s equipment was a substantial cause of the damage. Injury and wrongful death claims usually do require proof of fault.
Does inverse condemnation apply to the Palisades Fire?
The Palisades Fire is not an SCE case. Some victims have sued the City of Los Angeles, its water department and the State, and those claims raise different issues.
Does inverse condemnation cover emotional distress?
No. It covers property damage and related losses. Emotional distress and injury claims rely on other legal theories.
Is there a deadline to bring a claim?
Yes, and it depends on the claim and the defendant. Deadlines vary, so have a participating law firm review your dates soon.
Does it matter that SCE may have followed safety rules?
For inverse condemnation, generally no. Liability can attach even when a utility followed safety standards. For negligence and punitive damage claims, the utility’s conduct matters a great deal.
How Direct2Attorney can help
Direct2Attorney is not a law firm. We connect wildfire survivors with participating law firms that handle California wildfire claims. If you share your situation, a firm may review it at no cost and explain your options.
You can start on our California wildfire lawsuit page. There is no obligation, and a review does not commit you to anything.
Direct2Attorney is a legal marketing and referral service, not a law firm. This article is general information, not legal advice. Submitting information does not create an attorney-client relationship.