In this article (13 sections)
- Step 1: Understand the types of damages
- Step 2: See how big crash costs can be
- Step 3: Document every loss
- Step 4: Factor in fault
- Step 5: Know where the money comes from
- Step 6: Understand what reduces a payout
- Step 7: Don’t settle before you know the full picture
- How a Claim for Motor Vehicle Accident Compensation Usually Unfolds
- Talking With Insurance Adjusters: What to Keep in Mind
- Building a Simple Loss Worksheet
- Common Mistakes That Can Shrink Motor Vehicle Accident Compensation
- Motor vehicle accident compensation: frequently asked questions
- How Direct2Attorney can help
Last updated: October 2026
Motor vehicle accident compensation is usually built from two kinds of losses: economic damages, such as medical bills and lost wages, and non-economic damages, such as pain and suffering. What a claim may be worth depends on the injuries, the evidence, who was at fault and how much insurance is available. No one can promise a specific amount, but you can understand what goes into the number. Knowing how the claims process works, and which mistakes to avoid, can also help you protect your motor vehicle accident compensation from the very first call.
This step-by-step guide explains how injury compensation claims are typically valued and what you can do to document your losses.
Step 1: Understand the types of damages
Most injury claims include some mix of the following.
Economic damages
These are losses with a price tag:
- Emergency care, hospital stays and surgery
- Doctor visits, imaging, therapy and prescriptions
- Future medical care your doctors expect you to need
- Lost wages and lost earning ability
- Vehicle repair or replacement and damaged property
- Out-of-pocket costs, like rides to appointments or home help
Non-economic damages
These losses are real but harder to price:
- Physical pain
- Emotional distress, anxiety or sleep problems
- Loss of enjoyment of daily activities
- Scarring or disfigurement
Some states cap certain non-economic damages in some types of cases. Rules vary.
Wrongful death claims
When a crash is fatal, certain family members may be able to bring a wrongful death claim. Who can file and what can be recovered are set by state law.
Step 2: See how big crash costs can be
National data shows why careful documentation matters. The National Safety Council estimates these average economic costs per injury for 2024:
- Disabling injury: $174,000
- Evident injury: $45,000
- Possible injury: $28,000
NSC’s figures include wage and productivity losses, medical expenses, administrative costs, vehicle damage and employers’ uninsured costs. They are national averages, not claim values. NHTSA estimated crashes cost $340 billion in economic losses in 2019, and nearly $1.4 trillion when quality-of-life harms are included.
Step 3: Document every loss
A claim can only include losses that can be shown. Start a folder, paper or digital, and keep:
- All medical bills and records, including follow-up visits
- Pharmacy receipts and equipment costs
- Pay stubs, tax records or an employer letter showing missed work
- Repair estimates, rental car receipts and total-loss letters
- A daily journal of pain, sleep, limits and missed events
- Photos of injuries over time
The journal matters more than people think. It helps show non-economic losses that medical records do not capture.
Be specific. “Back hurt” says little, while “could not lift my daughter or sit through a work meeting” shows real impact. Note things you had to cancel, like trips, sports or family events, and tasks others had to do for you.
Lost income for self-employed or gig workers
If you are self-employed or work gig jobs, proving lost income can be harder. Tax returns, invoices, bank deposits and app earnings reports can help show what you normally earn and what you lost after the crash.
Step 4: Factor in fault
Fault can change the value of a claim. Cornell’s Legal Information Institute describes three general systems:
- Pure comparative negligence: Your recovery is reduced by your share of fault.
- Modified comparative negligence: Most states use this. You may recover only if your share of fault stays below a set limit, often 50% or 51%.
- Contributory negligence: Alabama, Maryland, North Carolina, Virginia and the District of Columbia may bar recovery if you were even slightly at fault.
For example, under a comparative system, a person found 20% at fault would typically have their damages reduced by 20%.
Because fault affects value so directly, insurers often focus on it. Evidence like photos, video, witness statements and the police report can help answer those arguments.
Other factors that move the number
Beyond fault and coverage, several practical factors often shape how a claim is valued:
- Severity and permanence: Injuries that need surgery or cause lasting limits usually carry more weight than injuries that heal quickly.
- Consistency of treatment: Steady, documented care supports the claim that an injury was serious.
- Pre-existing conditions: A crash that worsens an old injury may still support a claim, but insurers may argue about how much was new.
- Where the claim is filed: Local laws and court practices can affect outcomes.
Step 5: Know where the money comes from
Even a strong claim is limited by the insurance and assets available.
Liability coverage
In at-fault states, the other driver’s liability policy is often the main source. State minimum limits can be low compared with the cost of a serious injury.
No-fault benefits
In the dozen no-fault states listed by the Insurance Information Institute, personal injury protection (PIP) pays certain benefits first. You may only be able to claim pain and suffering from the at-fault driver if you meet your state’s threshold.
Uninsured and underinsured motorist coverage
The Insurance Research Council estimated that 15.4% of drivers were uninsured in 2023, and that underinsured rates rose in nearly every state from 2017 to 2023. Your own UM/UIM coverage can fill some of that gap.
Other sources
Employers, commercial carriers, vehicle makers or government agencies may share responsibility in some crashes, which can add coverage.
Step 6: Understand what reduces a payout
The amount you receive is often less than the total settlement. Common deductions include:
- Attorney fees and case costs, as set in a written agreement
- Liens from health insurers, hospitals, Medicare or Medicaid
- Amounts already paid by PIP or medical payments coverage
Ask any firm you work with to explain how these would be handled before you agree to a settlement. A written breakdown, sometimes called a settlement statement, should show the gross amount, each deduction and what you receive.
Step 7: Don’t settle before you know the full picture
Once you sign a release, you usually cannot ask for more money later. Before settling, it helps to know whether you have reached maximum medical improvement, meaning your condition has stabilized, and whether future care is expected. Filing deadlines still apply, and they vary by state and claim type, so waiting must be balanced against time limits.
How a Claim for Motor Vehicle Accident Compensation Usually Unfolds
Knowing what goes into the value of a claim is one part of the picture. Knowing how the process moves is the other. Most claims for motor vehicle accident compensation follow a similar path, though timing varies a lot.
Report the crash and open a claim
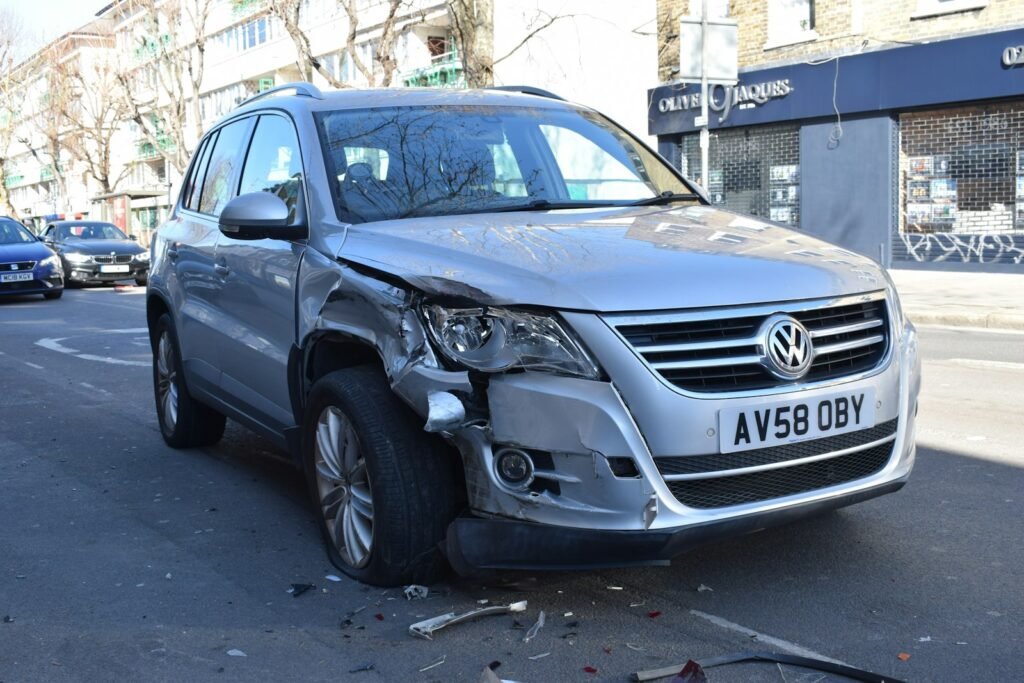
After a crash, the first priority is safety and medical care. Then the crash is usually reported to police and to the insurers involved. The National Association of Insurance Commissioners suggests calling the number on your proof-of-insurance card as soon as possible and keeping notes of the dates of any conversations with your agent or adjuster.
You will usually get a claim number. Write it down and keep it with your other records.
The adjuster’s investigation
An insurance adjuster reviews the crash. They may look at photos, the police report, vehicle damage and witness statements. They may also ask you for a recorded statement or for permission to collect your medical records.
Treatment and recovery
While you heal, your bills and records build up. Many claims for motor vehicle accident compensation are not fully valued until doctors have a clear view of your recovery, as the article explains in Step 7.
The demand package
When you are ready, a written demand is often sent to the at-fault driver’s insurer. It usually includes medical records and bills, proof of lost income, photos and a summary of how the injuries affected daily life. It ends with a request for a specific amount.
Negotiation
The insurer may accept, reject or make a lower counteroffer. Several rounds of back-and-forth are common. The NAIC notes that you should not feel rushed or forced to agree to something you are not comfortable with.
If the claim does not settle
If talks stall, a lawsuit may be filed before the deadline runs out. Filing does not mean the case will go to trial. Many cases still settle later. Deadlines vary by state and claim type.
How long the process may take
Simple property-damage claims can wrap up in weeks. Injury claims usually take longer, because treatment has to run its course before the full cost is known. Claims with serious injuries, disputed fault or several insurers may take a year or more, especially if a lawsuit is filed.
Waiting can be frustrating when bills are arriving. Ask about medical payments coverage, PIP or health insurance to help with costs in the meantime. Any of these may affect how the final motor vehicle accident compensation is split up, so keep track of what each one pays.
Talking With Insurance Adjusters: What to Keep in Mind
Adjusters are often friendly and helpful. But an adjuster for the other driver works for that driver’s insurer, not for you. Careful communication can help protect your motor vehicle accident compensation.
Helpful habits
- Stick to basic facts, such as the date, time and location of the crash.
- Keep a log of every call, including the date, the person’s name and what was said.
- Ask for important requests and offers in writing.
- Take time before answering questions you are unsure about.
Things to be careful about
- **Recorded statements.** You may not be required to give one to the other driver’s insurer. Ask a lawyer first if you are unsure.
- **Broad medical releases.** A release that covers your whole medical history may allow access to records unrelated to the crash.
- **Guessing.** If you do not know an answer, it is okay to say so.
- **Downplaying injuries.** Saying “I’m fine” out of habit can be used later, even if pain shows up days afterward.
If you disagree with your own insurer
For disputes with your own insurance company, the NAIC suggests asking for a written explanation, checking your policy for an appraisal clause and, if needed, asking your state insurance department’s consumer services staff for help.
Building a Simple Loss Worksheet
A loss worksheet puts every cost in one place. It can help you, and any law firm you work with, see the full value of your motor vehicle accident compensation claim. You can use a notebook, a spreadsheet or a folder with labeled sections.
Medical costs
- Ambulance and emergency room bills.
- Hospital, surgery and follow-up doctor charges.
- Physical therapy, chiropractic care and counseling.
- Prescriptions, braces, crutches and other equipment.
- Mileage or ride costs to and from appointments.
Income losses
- Days or hours missed from work, with your rate of pay.
- Paid time off or sick days you had to use.
- Missed overtime, bonuses or gig work.
- Any change in your ability to do your job going forward.
Property and other costs
- Repair estimates or total-loss value for your vehicle.
- Rental car or rideshare costs while your car was out of service.
- Damaged items inside the car, such as a phone, car seat or laptop.
- Help you had to pay for, such as child care, cleaning or yard work.
Daily life notes
Next to the numbers, keep short notes about how the injury changed your days. These notes support the non-economic part of motor vehicle accident compensation, which can be harder to show with bills alone.
Keeping the worksheet up to date
Update your worksheet once a week, or after each appointment. Small costs add up over months, and they are easy to forget. Keep the original bills and receipts in the same folder, in date order.
If you are unsure whether a cost counts, write it down anyway. A law firm can help you sort out what may be included in a claim for motor vehicle accident compensation and what may not.
Common Mistakes That Can Shrink Motor Vehicle Accident Compensation
People who are hurt are often busy, in pain and under stress. That makes it easy to make choices that reduce a claim’s value without meaning to. Here are some common ones.
- **Delaying medical care.** Gaps between the crash and your first visit can lead an insurer to argue the injury came from something else.
- **Skipping follow-up appointments.** Missed visits can be used to argue the injury was not serious.
- **Posting on social media.** Photos of activities, even short ones, can be taken out of context.
- **Throwing away records.** Receipts, bills and letters help prove your losses.
- **Repairing the car before photos are taken.** Damage photos can help show the force of the crash.
- **Settling too fast.** As the article explains, signing a release usually ends your claim for good.
- **Missing the deadline.** Filing deadlines vary by state and claim type, and some claims against government agencies have shorter notice rules.
Special situations
Some crashes raise extra questions. If you were a passenger, you may be able to claim against more than one driver’s policy. If you were a pedestrian or cyclist, your own auto policy may still provide some benefits in certain states. If a rideshare, delivery or commercial vehicle was involved, a business policy may apply.
Crashes involving a government vehicle or a dangerous road can also have special notice rules. These situations are a good reason to get a review early.
What to bring to a case review
You do not need everything in order before you ask for help. But having a few items ready can make a first conversation faster and more useful.
- The police report number, or the name of the officer and agency.
- Your claim numbers and the names of any adjusters you spoke with.
- Your own auto insurance declarations page, which lists your coverage.
- Photos of the scene, the vehicles and your injuries.
- Your loss worksheet, even if it is not finished.
- Any letters, emails or offers from insurers.
Bring copies, not originals, and keep the originals in a safe place at home.
Questions to ask a law firm
- What insurance coverage may be available in my crash, including my own policy?
- How might fault rules in my state affect my motor vehicle accident compensation?
- Should I give a recorded statement, and to whom?
- How will liens and medical bills be handled at the end?
- How are fees and costs calculated, and can I see the agreement in writing?
A participating law firm may review your crash, your injuries and your coverage. Asking these questions early can help you understand your motor vehicle accident compensation options before key decisions are made.
Motor vehicle accident compensation: frequently asked questions
Is there a formula for car accident compensation?
No single formula applies. Insurers weigh medical costs, lost income, injury severity, fault, evidence and policy limits. Every claim is different.
Can I be paid for pain and suffering?
In many cases, yes. In no-fault states, you may need to meet a threshold first. State caps may apply in some situations.
What if my medical bills are higher than the driver’s insurance?
Your own underinsured motorist coverage may help. Other responsible parties may also have coverage.
Are settlements taxed?
Tax treatment depends on the type of payment. Talk with a tax professional about your situation.
Does a bigger crash always mean a bigger claim?
Not always. Vehicle damage can support an injury claim, but serious injuries can happen in crashes that look minor. Medical evidence usually matters more than the repair bill.
How Direct2Attorney can help
Understanding motor vehicle accident compensation can help you make informed choices about your claim. Direct2Attorney can connect you with a participating law firm that may review your injuries, losses and insurance at no cost to you. Visit our motor vehicle accident page to see if you may qualify.
Direct2Attorney is a legal marketing and referral service, not a law firm. This article is general information, not legal advice. Submitting information does not create an attorney-client relationship.